Understanding sales and service tax helps you avoid surprises. The sales and service tax was reintroduced on 1 September 2018 under the Sales Tax Act 2018. The Royal Malaysian Customs Department oversees collection and remittance, while consumers ultimately bear the consumption cost.
For many small businesses, the key question is when to act. This guide explains how the single-stage tax applies at the manufacturing or service provision point. It also shows how sales and goods obligations affect daily cash flow and long-term planning.
We break down core requirements so you can comply with the customs department and avoid common pitfalls. By managing sales, tax reporting, and goods services correctly, your business stays focused on growth and delivering value to customers.
Key Takeaways
- Sales service tax is a single-stage consumption tax charged at production or service delivery.
- The Royal Malaysian Customs Department handles collection and remittance.
- Businesses collect tax from consumers and remit it to authorities.
- Know thresholds and registration rules to avoid penalties.
- Proper record keeping for goods services reduces audit risk.
Understanding the Basics of SST
Understanding how the sales and service tax works helps business owners price products and plan cash flow. This section explains what the levy covers and how the single-stage approach operates.
What is the Sales and Service Tax
The system replaced the earlier GST on 1 September 2018 to simplify indirect taxation. Sales tax applies to taxable goods made or imported into the country. Service tax targets specific services at the point of consumption.
Single-Stage Taxation Explained
The single-stage model means tax is charged once—usually when goods are manufactured or when services are supplied. This design prevents tax compounding across the supply chain.
- Sales tax targets taxable goods at manufacture or import.
- Service tax covers many services and is charged at sale or delivery.
- Consumers ultimately pay the tax as part of the final price.
Key benefit: the simpler framework makes compliance clearer and reduces pricing surprises for customers and sellers alike.
Why SST Registration Malaysia is Essential for Your Business
Mandatory tax thresholds mean your business may soon need to start charging for certain goods and services. If annual turnover exceeds RM500,000, the law requires action to stay compliant. Proper enrollment lets companies legally collect and remit sales tax and service tax to the government.
Failing to comply brings real risks. Penalties and legal consequences can disrupt daily operations and hurt cash flow. Small and medium businesses often underestimate this impact until enforcement occurs.
Beyond avoiding fines, formal compliance adds transparency. The current system replaced the old goods services tax and aims to balance revenue needs with fair treatment across industries.
- Follow the RM500,000 threshold. Meet it and you must act.
- Collect and remit correctly. This preserves trust with customers and regulators.
- Protect your business. Proper steps reduce audit risk and financial shocks.
Determining Your Eligibility for Tax Registration
Start by calculating your taxable turnover for the past 12 months. This figure decides whether you must enroll for the sales and service tax scheme. Use actual sales and billed services when totaling revenue.
Threshold Requirements
The standard cutoff is RM500,000 in annual turnover. Businesses must assess taxable goods and taxable services separately. If either category exceeds the threshold, that part of your business becomes liable.
Count revenue from the preceding 12 months. If you cross RM500,000, authorities expect you to act within 30 days.
- Monitor turnover monthly. Tracking helps spot when you near the threshold.
- Project future sales. Forecasts that show crossing the cutoff soon may also trigger the duty to apply.
- Keep clear records. Accurate figures prevent late fees and disputes.
Sales Tax Versus Service Tax Explained
Understanding which levy applies removes guesswork when you sell a product or charge for a service. Sales tax targets goods made or imported and is usually charged at manufacturing or import points. Typical sales tax rates are 5% or 10%.
Service tax applies to prescribed services and is collected at the point of service from consumers. Common rates are 6% or 8%, depending on the service category.
There is no input tax credit under this regime, so businesses cannot recover tax on purchases the way they could with the old GST. That makes correct classification of goods and services vital.
- Sales tax covers taxable goods and focuses on manufacturing and import stages.
- Service tax covers a broad range of services from F&B to consulting and logistics.
- Consumers pay service tax as an extra charge; businesses collect and remit it.
- Clear separation between sales tax service obligations helps avoid reporting errors.
| Aspect | Sales Tax | Service Tax | Impact |
|---|---|---|---|
| Applied to | Taxable goods | Prescribed services | Determines point of collection |
| Typical rate | 5% or 10% | 6% or 8% | Affects pricing and margins |
| Collection point | Manufacturer or importer | Business at service point | Who remits tax to authorities |
| Input tax credit | Not allowed | Not allowed | Higher compliance focus on cost management |
Current Tax Rates and Thresholds
Know the current rates and thresholds so your pricing and forecasts stay accurate. This section summarizes the prevailing sales and service tax structure and highlights recent expansions that affect many businesses.
Sales Tax Rates
Sales tax generally applies at either 5% or 10%, depending on the type of goods manufactured or imported. Manufacturers should classify products carefully to pick the correct rate.
Correct classification avoids undercharging customers and reduces the risk of penalties.
Service Tax Rates
Most service tax items now carry an 8% standard rate. Essentials such as food and logistics remain at 6% to keep basic services affordable.
Businesses offering professional or prescribed services must review whether their offerings are taxable services and apply the right rate.
New Categories and Expansion
As of 1 July 2025, new categories — including construction and private healthcare — were added to the scope. For construction, the registration threshold is RM1,500,000 to reflect larger project values.
There was a penalty-free compliance period until 31 December 2025. Even after that period, monitoring thresholds and rates is a continuous task for any business that provides taxable services or goods.
- Structured rates balance revenue needs and affordability.
- Track rate changes and classify sales and services correctly.
- Review thresholds regularly to stay compliant with new expansions.
Exemptions and Zero-Rated Goods
Essential items and select exports often escape tax to keep prices fair and support trade. The list protects staples like rice, chicken, and local fish so households pay less for basic supplies.
Other exempt goods include books, medicines, and basic building materials. Manufacturers that make goods for export also benefit from exemptions to stay competitive abroad.
“Always check the official list for the latest changes.”
- The government exempts essential goods to protect affordability for citizens.
- Zero-rating helps keep medicines, books, and staple food items accessible.
- Exported goods receive relief to encourage trade and lower costs.
- From 1 July 2025, certain imported fruits like apples and oranges were added to the exempt list.
- Businesses should review the MySST site regularly and keep clear records of exempt items.
Tip: Maintain accurate documentation for exempt goods to simplify reporting and avoid errors during audits.
Preparing Necessary Documentation
Gathering the right paperwork makes the application smoother and speeds up approval.
Required Business Records
Start by collecting formal proof of your business identity. Include your business registration certificate such as SSM for local entities. Keep a clear copy of owner or director ID (passport or identity card).
Financial statements are essential to show annual turnover for sales tax threshold checks. Prepare audited or management accounts that match your tax filing periods.
- Bank account details for refunds or payments.
- Organized sales and service records to support declared turnover.
- Invoices, contracts, and shipment papers that prove taxable transactions.
| Document | Purpose | Tip |
|---|---|---|
| Business registration certificate | Proves legal existence | Keep a certified copy |
| Financial statements | Verify turnover for registration | Use latest 12-month figures |
| Director/owner ID & bank details | Confirm identity and payments | Match names across forms |
| Sales ledgers & invoices | Support tax filings and audits | Store electronic backups |
Tip: Keep records up to date and easy to retrieve. When you choose to register sst and complete registration steps, tidy documents will cut delays and reduce follow-up queries from the customs office in Malaysia.
Navigating the MySST Portal
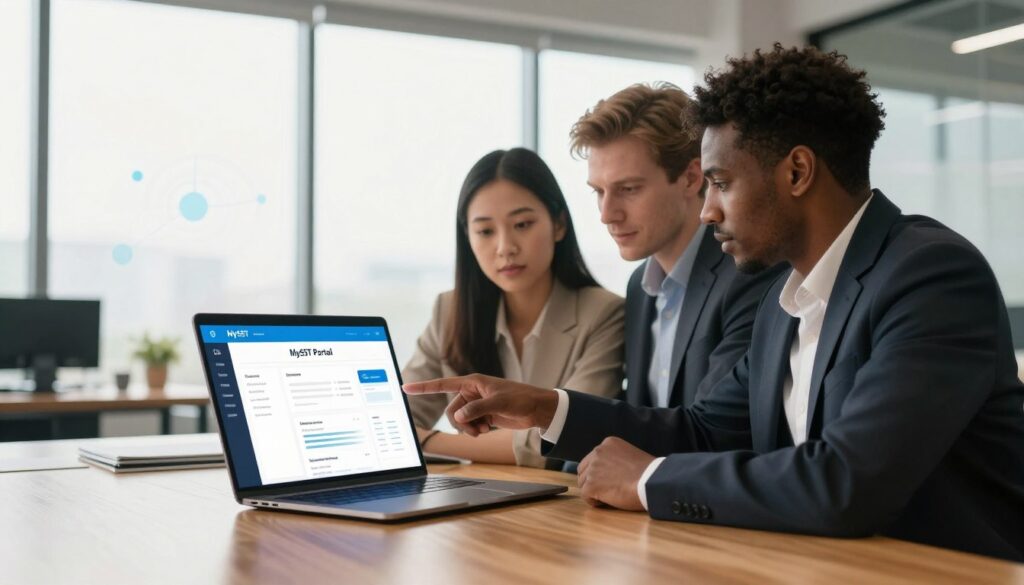
The MySST portal guides first-time users through simple screens to capture business details and necessary documents. Start by choosing the “New Registration” option and follow each step carefully.
Prepare your files. Have your company records, financial statements, and proof of identity ready. This speeds the form and reduces follow-ups from the customs department.
After you submit, the system sends your application to the Royal Malaysian Customs for verification. Once approved, you will get an approval letter and an email with all approval details. Keep these for your records.
The portal also lets you manage service tax and sales services, view obligations, and update contact information. If you need to register sst for new activities, the site supports both sales and service registration paths.
- Easy online steps for first-time applicants.
- Portal tools to track approval and manage accounts.
- Support resources from the royal malaysian customs if issues arise.
| Step | Action | Outcome |
|---|---|---|
| New Registration | Enter business details and upload documents | Application submitted to customs department |
| Verification | Department reviews submitted information | Approval letter issued if complete |
| Post-Approval | Receive email with approval details | Start charging and reporting service tax |
Understanding the Future and Historical Threshold Tests
Two simple tests decide when your business crosses the legal turnover line for tax duties.
The historical test adds your current month to the previous 11 months to calculate taxable turnover. If that total passes the RM500,000 threshold, you must register and begin charging tax.
The future test sums your current month plus expected monthly turnover for the next 11 months. Growing firms that expect to exceed RM500,000 under this method also must register within 30 days.
Both methods exist so businesses start compliance as soon as they become liable. Monitor figures each month and keep simple forecasts. This helps avoid penalties and sudden cash-flow shocks.
- Register if you cross RM500,000 under either the historical or future turnover test.
- Track taxable turnover monthly and update your projections regularly.
- Act within 30 days of the month you expect to breach the threshold to stay compliant over the years.
“Consistent monitoring of turnover is the easiest way to avoid late registration penalties.”
Managing Post-Registration Obligations
Once your business completes formal enrollment, new filing and record duties begin immediately. Stay organized to avoid late fees and confusion.
Filing Returns
Registered businesses must submit the SST-02 return every two months. This bi-monthly form reports tax collected on your services and any taxable supplies.
Payments for service tax and sales tax are due by the last day of the month after the taxable period. The type of services provided affects what you report on each SST-02 filing.
E-Invoicing Mandates
The government is rolling out a phased e-invoicing system through MyInvois to boost transparency. Adopting the e-invoicing system helps automate bills and link invoices to returns.
Keep detailed records for at least 7 years. Proper documentation of all services provided protects your business during audits and simplifies reconciliations.
- File bi-monthly returns to declare tax on services and other taxable items.
- Adopt MyInvois e-invoicing to streamline reporting and billing.
- Document every service provided accurately to avoid discrepancies in SST-02 submissions.
- Monitor filing deadlines and pay on time to prevent penalties.
- Retain financial records for seven years to meet audit requirements.
“Integrating e-invoicing will reduce manual errors and speed up compliance.”
Consequences of Non-Compliance and Penalties
Failing to meet service tax obligations exposes businesses to escalating fines and legal action. Enforcement is active now, so acting quickly matters.
Failure to register or to file required returns can result in fines up to RM50,000 or imprisonment for up to three years. The law treats missed filings and non-payment seriously.
Late payment penalties rise by period: 10% for the first 30 days, 15% for delays of 31–90 days, and up to 40% after 90 days. These penalties aim to encourage timely remittance.
There was a penalty-free grace period until 31 December 2025 to help firms adapt. That period has ended, so ongoing compliance is essential for all businesses.
| Offense | Consequence | Timeline / Period |
|---|---|---|
| Failure to register or file | Fines up to RM50,000; up to 3 years imprisonment | Immediate enforcement |
| Late payment (0–30 days) | Penalty: 10% | First 30 days |
| Late payment (31–90 days) | Penalty: 15% | 31–90 days |
| Late payment (>90 days) | Penalty: Up to 40% | After 90 days |
Protect your company: keep clear filing schedules, record payments, and seek help early to avoid heavy penalties and long-term harm to cash flow.
Getting Professional Assistance at +60143422168
A short call with a specialist can pinpoint your obligations and stop small errors before they grow. If you want a clear guide through the process, call +60143422168 for friendly, practical help.
Our team simplifies steps and saves you time. We explain which documents matter, how to calculate turnover, and what to file next.
- Call +60143422168 if the process feels overwhelming; experts will walk you through each step.
- We can help you correctly register sst malaysia and meet legal obligations without guesswork.
- Expert support reduces common mistakes that lead to audits or penalties.
- Get a clear guide tailored to your business activities and turnover.
- Let us handle the paperwork so you can focus on daily operations.
- Our consultants stay updated with customs rules to keep your filings accurate and timely.
Tip: Phone advice at +60143422168 often avoids delays and costly errors.
Conclusion
Close attention to your turnover and categories keeps your business out of costly compliance trouble.
Malaysia’s sales service tax remains a core part of the national revenue system and affects many small businesses. Proper sst registration stops legal penalties and protects your cash flow.
This guide outlined how to check eligibility, gather documents, and use the official portal. Stay alert to threshold changes and new taxable categories as the system evolves.
Review financial records regularly and update forecasts so your turnover calculations stay accurate. By taking proactive steps now, you secure the future of your business and limit disruption from audits or fines.
FAQ
Does my small or medium-sized business need to register for sales and service tax?
You must register if your taxable turnover meets the threshold for sales or service tax within a 12-month period. Check both historical and projected turnover. If your goods or services fall under taxable categories and you cross the prescribed limit, registration is required to comply with the law and avoid penalties.
What is the sales and service tax and how does it work?
The sales and service tax is a single-stage consumption tax applied to certain goods at manufacture or import, and to specific services at the point of supply. It’s collected by registered businesses and remitted to Royal Malaysian Customs. Rates vary by product or service type, and businesses must issue proper invoices and keep records.
What does single-stage taxation mean for my business?
Single-stage taxation means tax is charged once along the supply chain—either at manufacture, import, or when the service is supplied. It simplifies compliance compared with multi-stage systems, but you must correctly identify taxable supplies and apply the right rate.
How do I determine if my turnover meets the threshold requirements?
Calculate taxable turnover by adding sales of taxable goods and taxable services over the relevant period. Use both past 12 months and projected next 12 months tests. If either exceeds the threshold set by the authority, you must register. Keep clear ledgers to support your calculations.
What’s the difference between sales tax and service tax for my offerings?
Sales tax applies mainly to manufactured or imported goods at the manufacturer or importer level. Service tax applies to specific taxable services provided to consumers or businesses. Some supplies may be exempt or zero-rated, so classify each product or service correctly.
Where can I find current tax rates for goods and services?
Rates are published by the Royal Malaysian Customs. Sales tax rates depend on the tariff classification of goods, while service tax uses set percentage rates for listed services. Check official schedules regularly because new categories and expansions can change rates.
Which goods and services are exempt or zero-rated?
Exempt and zero-rated items are listed in the legislation and official guidance. Common examples include certain essential food items, health services, and exported goods. Zero-rated supplies are taxable but charged at 0%, allowing input relief where applicable; exempt supplies do not allow input claims.
What documents and records do I need before registering?
Prepare business registration, identity details of proprietors or directors, bank account information, recent financial statements, sales ledgers, purchase records, and details of taxable activities. Accurate documentation speeds up approval and supports future audits.
How do I use the MySST portal to register and manage tax accounts?
Register an account on the portal using your business details, upload required documents, and follow the guided registration flow. The portal supports filing returns, paying tax, and updating registration particulars. Keep login credentials secure and update records promptly.
What are the historical and future threshold tests I should monitor?
The historical test looks at turnover over the previous 12 months; the future test projects the next 12 months. If either test exceeds the threshold, registration is mandatory. Regularly review sales trends and adjust forecasts to remain compliant.
What are my filing obligations after registering?
Registered businesses must submit periodic returns through the portal, remit collected tax by due dates, and maintain accurate accounting records. Filing frequency and deadlines depend on the tax type. Late submissions can trigger penalties and interest charges.
Are there e-invoicing or digital invoicing requirements?
Digital invoicing mandates evolve; some sectors must adopt e-invoicing or comply with format standards for tax invoices. Use compliant software and keep electronic records for audits. Check the customs department’s technical guides for current mandates.
What penalties apply if I fail to register or comply?
Penalties include fines, interest on unpaid tax, and potential prosecution for serious breaches. The authority may assess back taxes and administrative penalties. Prompt voluntary disclosure and corrective action can reduce sanctions.
When should I seek professional help and how can I contact an advisor?
Consult a tax agent or qualified accountant when you face complex classification issues, large turnover changes, cross-border supplies, or audit notices. For immediate assistance, call +60143422168 to discuss registration steps, record-keeping, or filing support.